How we arrange your business mortgage, step by step
Seven stages from the first conversation to completion. You deal with the same person throughout, and we keep the valuation, the lender and the solicitors moving.
First conversation
You tell us the premises, the price or value, the deposit and how the business trades. We tell you plainly whether it is fundable and roughly on what terms.
The accounts
We read two to three years of accounts, recent management figures and bank statements, and work out the EBITDA and debt service cover a lender will see.
Lender selection
We shortlist the high-street, challenger and specialist lenders whose criteria fit your sector, the building and the loan size.
Indicative terms
We present the case and bring back indicative terms: rate, loan to value, term, fees and any covenants or personal guarantees.
Valuation and credit
You choose a lender. It instructs an independent RICS valuation and takes the case to its credit committee. We handle the questions.
Offer and legals
The lender issues a facility letter. Your solicitor and the lender's solicitor complete the title work, searches and the charge or standard security.
Completion
Funds are released, the purchase or refinance completes, and the business owns, or keeps owning, the premises it trades from.
Timescales are typical, not promises. Commercial lending to a limited company is unregulated; where a deal would be regulated we refer it to an appropriately authorised firm.
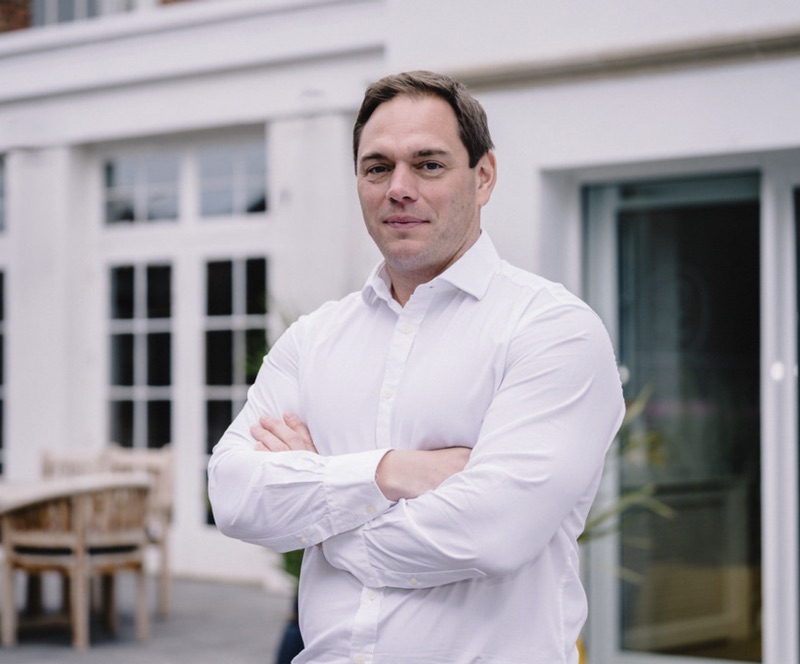
A business mortgage is won or lost on how the accounts are presented. I've spent 25 years in financial services, raising debt and equity, and every case still comes through me: the accounts, the credit conversation, the valuation and the legals. You deal with the person arranging your mortgage, not a call centre.
- 25 yearsin financial services, raising debt and equity
- £400m+property finance arranged
- 1 personon your case from first call to completion
The process: questions
How long does a business mortgage take?
A purchase usually takes several weeks from choosing a lender to completion, driven mainly by the valuation and the legal work, and we give you a realistic timescale at the start. A refinance can be quicker. Where you have a hard deadline, such as an auction, bridging can complete first and refinance onto a mortgage afterwards.
What do you need from me to start?
Only an outline: the premises, the price or value, your deposit and a picture of how the business trades. Accounts and management figures come next, once we know the deal is worth taking to market.
Do you charge a fee?
There is no charge to enquire or to get indicative terms. Where a broker fee applies to a facility we agree it with you in writing before you commit, alongside the lender's own fees.
Do you lend the money?
No. We are a finance arranger and introducer, not a lender. We take your case to lenders and act for you, the borrower.
Tell us about the premises
Send us the property, the price and a picture of how the business trades. We will come back with a view on what the market is likely to offer, usually within one working day. There is no charge to enquire.
 Matt Lenzie reads every enquiry himself.